Financing a Condo in Florida: What Buyers, Sellers, and Investors Need to Know Now
Financing a condominium in Florida has always come with unique nuances, but recent regulatory changes have fundamentally reshaped the landscape.
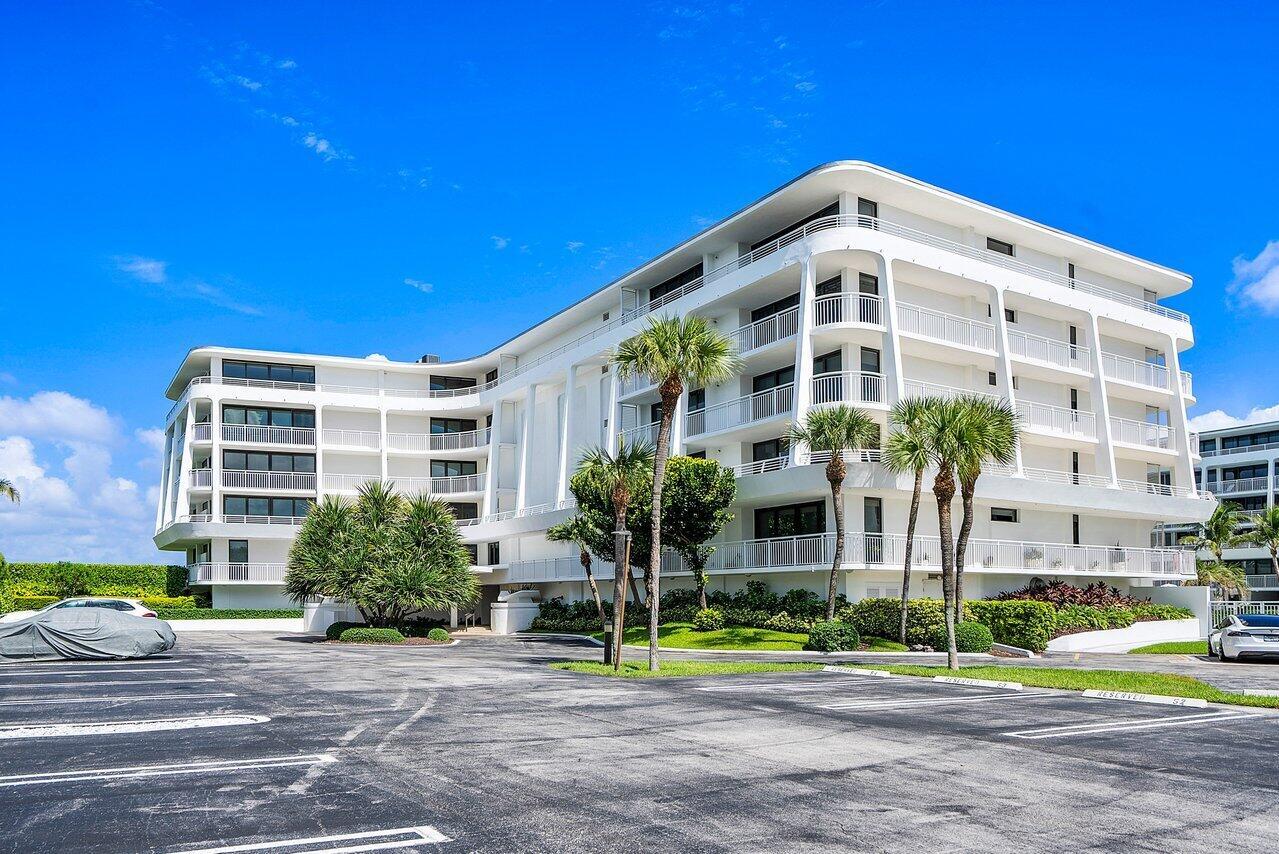
Over the past few years, major updates to both state laws and federal lending requirements have added strict new layers of review for condo purchases. Mortgage giants Fannie Mae and Freddie Mac eliminated the old "Limited Review" shortcut.Today, lenders perform full, comprehensive reviews of a condo association’s health—scrutinizing structural integrity, maintenance history, and balance sheets.
Key changes impacting the market include:
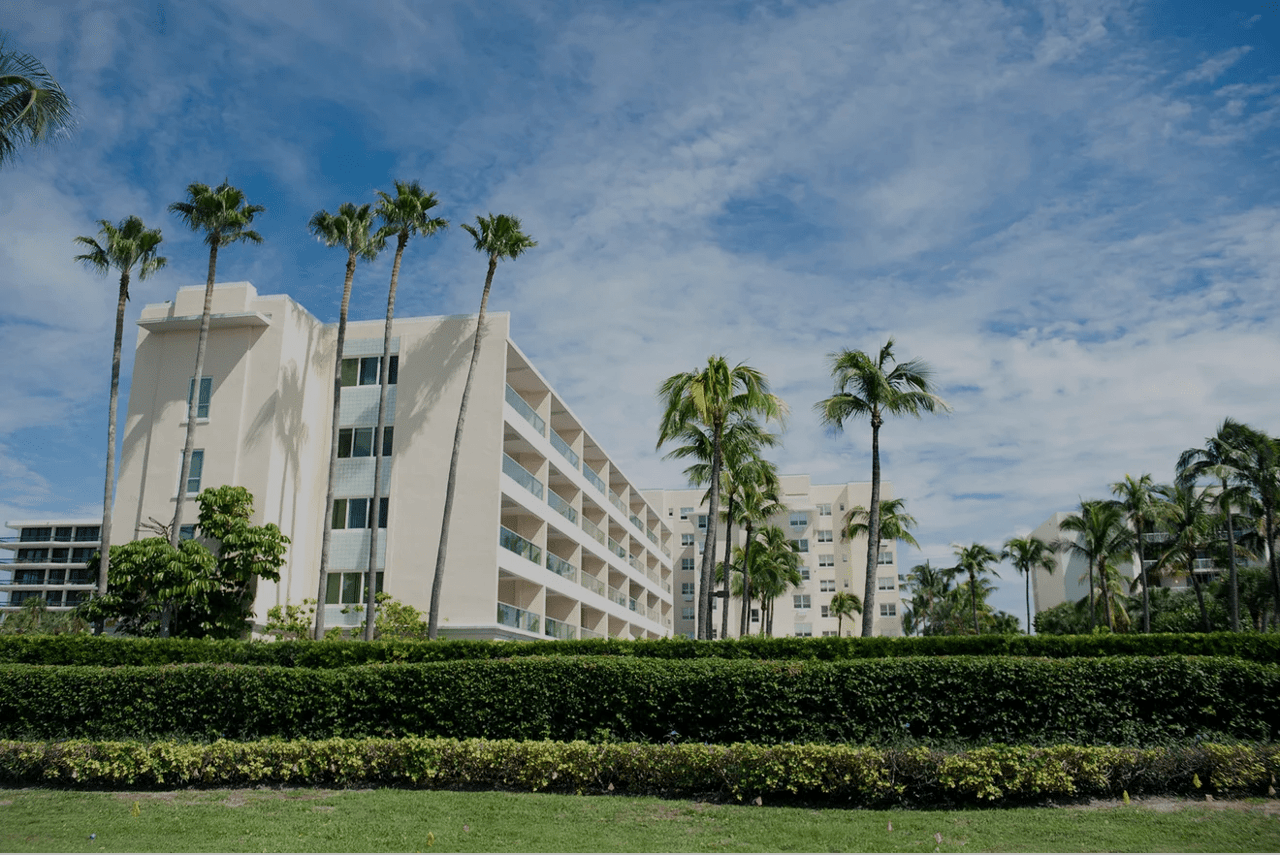
- Strict Structural Integrity Reserve Studies (SIRS): Associations with buildings three or more habitable stories high must complete SIRS assessments and fully fund structural reserves—unit owners can no longer vote to waive or reduce these structural reserves.
- Higher Reserve Funding Standards: Lenders are holding condo association budgets to stricter standards, including higher replacement reserve expectations, to ensure buildings have adequate cash flow for upkeep.
- Stricter Full Reviews for All Buyers: Even well-qualified buyers with large down payments face thorough project approvals, where deferred maintenance or ongoing assessments can stall conventional loan underwriting.
For buyers and sellers in high-demand markets like Palm Beach, securing conventional financing now takes strategic planning. That is why more buyers are turning to alternative financing—such as portfolio and Non-QM (Non-Qualified Mortgage) loans—to keep their deals moving forward.
The Next Move Is Yours
Navigating Florida’s evolving condo market requires proactive guidance. Whether you are listing a condo or shopping for your next home, staying ahead of these lending shifts is key to a smooth closing.
Scott Gordon
(561) 346-4141
Mindy Gordon
(561) 302-3133